What is the scope and industry significance of the K-12 Online Education Market?
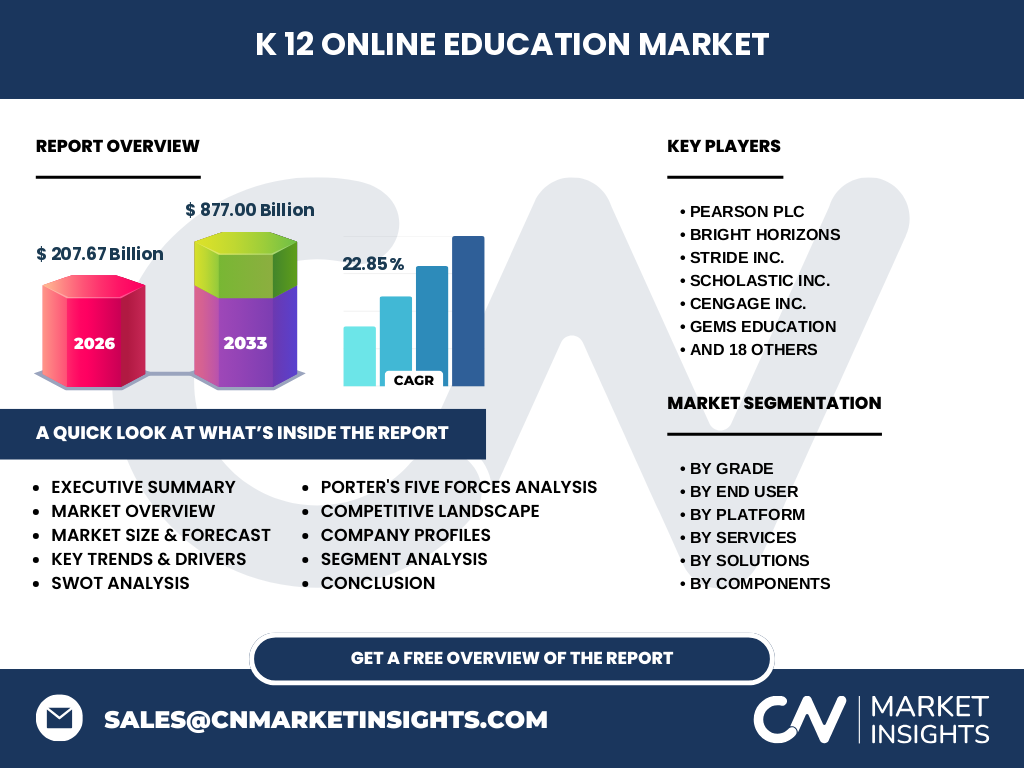
Our analysis indicates that the K-12 Online Education Market is scaling rapidly, valued at 207.67 Billion in 2026. This sector encompasses digital platforms, virtual classrooms, and curriculum content serving students from Kindergarten through High School, fundamentally transforming how educational institutions deliver core academic instruction.
Key market drivers, restraints, challenges, and opportunities shaping the K-12 Online Education Market
Growth is propelled by accelerated cloud adoption and mobile learning initiatives. However, regulatory hurdles regarding data privacy compliance, such as COPPA and FERPA mandates, act as key restraints. Despite infrastructure gaps in rural districts, the surging demand for personalized learning creates vast opportunities for providers utilizing adaptive algorithms.
Emerging trends and growth patterns in the K-12 Online Education Market
The shift toward gamification and Big Data and Analytics is redefining student engagement. Schools increasingly rely on predictive analytics via platforms like those from Lightspeed Systems Inc. to track student progress, moving away from rigid, one-size-fits-all curricula toward highly customizable digital pathways.
COVID-19 impact analysis and recovery trajectory for K-12 Online Education Market
The pandemic served as an unprecedented catalyst, forcing immediate migration to cloud-based virtual learning environments. While initial emergency remote teaching highlighted severe digital divides, post-recovery investments have permanently institutionalized hybrid schooling models, laying the groundwork for sustained long-term market expansion.
Competitive benchmarking and strategic dynamics in the K-12 Online Education Market
The competitive landscape is characterized by high fragmentation alongside aggressive consolidation by publishing giants. Industry leaders like Pearson Plc and Stride Inc. leverage massive content libraries and proprietary LMS platforms to capture institutional contracts, squeezing smaller edtech startups out of major school districts.
Executive summary of key findings for the K-12 Online Education Market
Our comprehensive research projects the K-12 Online Education Market to surge from 207.67 Billion in 2026 to an astounding 877.00 Billion by 2033, expanding at a robust CAGR of 22.85%. This exceptional trajectory is driven by permanent shifts toward digital-first pedagogical frameworks.
Market forecast from 2027 to 2033 for the K-12 Online Education Market
Driven by widespread deployment of cloud infrastructure and advanced assessment tools, the market will scale aggressively from 2027 through 2033. Achieving a CAGR of 22.85% to reach 877.00 Billion by 2033, growth will be heavily concentrated in SaaS-based delivery models and specialized managed services.
Segmentation analysis across grade levels, end users, platforms, services, solutions, components, and deployment
Segmentation spans multiple dimensions: by Grade (Kindergarten, Elementary, Middle School, High School); End User (Schools, Individuals, Private Tutors); Platform (Gamification, Mobile, Tablet, Laptops/Chromebooks, Big Data/Analytics, LMS); Services; Solutions; Components; and Deployment (Cloud, On-Premises). Each segment addresses distinct institutional workflows and learner requirements.
Regional market analysis and geographic distribution within the K-12 Online Education Market
Geographic performance varies significantly, with North America leading in market share due to mature broadband infrastructure and high device-to-student ratios. Meanwhile, Asia-Pacific exhibits the fastest adoption rates, propelled by government-backed digital literacy initiatives in emerging economies and massive enrollments via platforms like TAL Education Group.
In-depth regional review of the K-12 Online Education Market
North American growth is underpinned by robust K-12 tech budgets and widespread Chromebook penetration. In contrast, the European landscape faces stringent GDPR constraints that shape vendor selection, favoring local compliance-first solutions over generic international offerings, while Middle Eastern markets like GEMS Education expand premium private digital portfolios.
Company profiles and strategic positioning of leading participants
Major industry players occupy distinct strategic niches. Stride Inc. and Pearson Plc dominate full-time online schooling and standardized curriculum publishing, whereas Duolingo and Chegg capture supplemental individual learning demand through freemium and direct-to-consumer mobile applications.
Porter's Five Forces analysis of the K-12 Online Education Market
Supplier power remains moderate due to standardized curriculum requirements, but buyer power is high as school boards demand rigorous cost-effectiveness. The threat of new entrants is mitigated by high regulatory barriers and the deep institutional relationships enjoyed by established giants like McGraw-Hill Education and Houghton Mifflin Harcourt.
SWOT analysis of the K-12 Online Education Market ecosystem
Key strengths include scalability and personalized learning capabilities. Weaknesses involve cybersecurity vulnerabilities and uneven broadband access. Opportunities lie in AI-driven tutoring integrations, while threats stem from tightening federal compliance mandates and potential data privacy breaches affecting student records.
Value chain analysis detailing industry structure and value flow
The value chain flows from raw educational content creation—driven by authors and instructional designers at firms like Great Minds—through digital platform development and cloud deployment, ultimately delivering SaaS solutions to schools, private tutors, and individual students via secure LMS interfaces.
Investment insights and high-potential areas within the K-12 Online Education Market
Investors should target B2B SaaS providers specializing in Assessment and Evaluation Tools and Consulting and Integration Services. Companies capable of integrating AI-driven analytics with existing school district IT frameworks present the highest potential for margin expansion and scalable enterprise contracts.
Conclusion and key takeaways for stakeholders
The K-12 Online Education Market represents a transformative investment frontier. With a forecasted valuation of 877.00 Billion by 2033, stakeholders must prioritize cloud-native architectures, regulatory compliance, and localized content customization to capture long-term market share successfully.
Research methodology for the K-12 Online Education Market report
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with edtech executives, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of segments ranging from Kindergarten to High School across global regions.
Scope of the report, coverage parameters, and analytical limitations
This report covers global K-12 online education dynamics from 2026 to 2033, analyzing solutions, services, deployment models, and end-user segments. Limitations include unforeseen regulatory shifts in localized municipal education budgets and rapid technological obsolescence cycles inherent to software-driven markets.
Recent developments, company announcements, partnerships, and strategic moves
Recent market activity highlights aggressive strategic partnerships, such as Instructure Inc. integrating advanced AI capabilities into its Canvas LMS, and Amplify launching targeted literacy interventions. These moves demonstrate a clear industry pivot toward enhanced personalization and data-driven student performance tracking.